

Bill Payment Reminder, Budgets
by TimelyBills
4.5
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.5
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
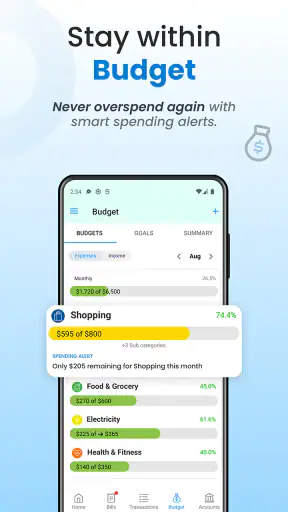
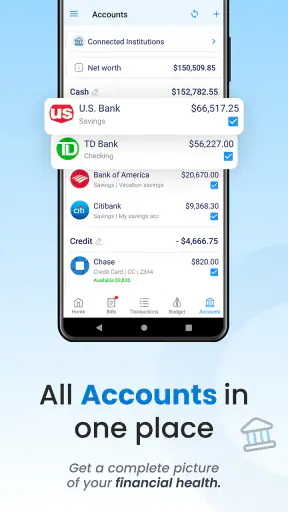
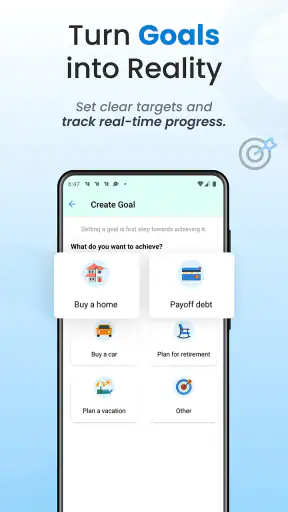
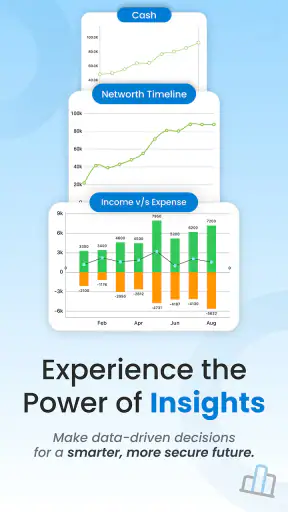
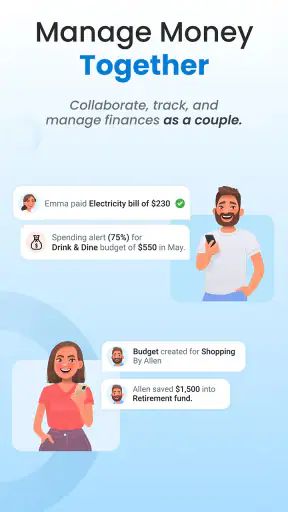
 Analysis by Getfullapps
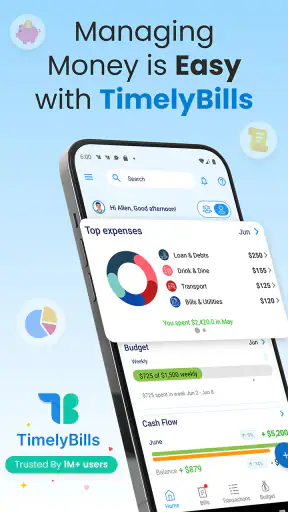
Managing bills is rarely difficult because of one large payment. The trouble usually comes from several small deadlines arriving at different times, subscriptions being forgotten, and household spending becoming hard to see. Bill Payment Reminder, Budgets is designed for that everyday problem. It is a finance app from TimelyBills that brings bill reminders, payment tracking, budgeting, and family money management into one place.
I found its main appeal in the simple routine it encourages: record what needs to be paid, give each item a useful date, and check the plan before money leaves the account. It does not try to replace a bank, and that is important to understand from the start. Instead, it works as a personal money organizer that helps you remember obligations and make your monthly picture easier to read.
The app is free to install and is suitable for everyone. It has been available since May 23, 2015, and its current Android version is 1.26.027, with Android 8.0 or later required. With more than a million installs and an average rating of 4.5 from roughly thirty-seven thousand ratings, it has clearly found an audience among people who want a dedicated place for bill planning rather than relying on notes, calendar alerts, or memory.
What the app feels like in everyday use
My first impression is that the app is most useful when treated as a financial dashboard rather than a one-time reminder tool. A single reminder for rent is easy to create in almost any calendar. The stronger case for this app appears when you want to see several recurring bills together, compare them with a budget, and keep a record of whether they were paid.
That distinction matters for choosing the right tool. A calendar is excellent for a handful of fixed appointments, while a spreadsheet gives you more freedom to build custom calculations. Bill Payment Reminder, Budgets sits between those options. It offers more structure than a simple list, but it is less demanding than maintaining a spreadsheet every month.
I would recommend it first to someone who regularly says, “I knew the bill was coming, but I forgot to set the money aside.” It can also suit couples or families who need a shared view of household obligations. The family budgeting angle is useful when one person handles rent, another handles utilities, and both need a common reference point.
The most important mindset is to use the app before a bill becomes urgent. If you only open it after a payment is late, it becomes a record of problems. If you update it when a bill arrives or when a payment is made, it becomes a simple planning habit.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
What it does not replace
This is not the same as automatic bill payment through a bank. The app helps you organize and track payments, but you should still follow the payment instructions for each service and confirm that a transaction has actually gone through. I would not rely on a reminder alone for a critical obligation without checking the account or provider afterward.
It is also not a full accounting system for a small business. If you need invoices, inventory, tax categories, detailed reports, or complex reconciliation, a bookkeeping application will be a better match. This app is aimed at personal and household money organization, where clarity and consistency matter more than professional accounting depth.
Starting with a small, useful set of bills
When I begin with a budgeting app, I prefer not to enter every financial detail immediately. That approach often creates a large setup task and makes the app feel like work. A better first step here is to add the bills that cause the most stress: housing, utilities, insurance, loan payments, school costs, or recurring subscriptions.
For each item, I would enter the name in a way that makes sense at a glance. “Electricity” is more useful than a vague label such as “monthly payment.” If two people use the same account, clear naming becomes even more important because the list should be understandable without explanation.
Next, I would add the due date and expected amount as accurately as possible. If an amount changes from month to month, I would treat the first figure as a planning estimate and review it when the actual bill arrives. That small distinction prevents a budget from looking precise when the underlying payment is variable.
There is a practical benefit to adding bills in order of consequence rather than convenience. A missed entertainment subscription may be annoying, but a missed housing or utility payment can create much more serious trouble. Entering the high-priority items first means the app starts helping even before the full household budget is built.
Making the first setup less overwhelming
I would set aside a few minutes with recent statements or provider messages nearby. The goal is not to reconstruct your entire financial history. It is to create a forward-looking list that answers three questions: what is due, when is it due, and how much should be available?
For recurring payments, consistency is more valuable than excessive detail. Use the same naming style, keep amounts realistic, and avoid creating multiple entries for the same obligation. Duplicate entries can make the total look worse than it is and may lead you to think you have more payments than you actually do.
Families should agree on who updates an item after payment. If both people mark the same bill independently, the record can become confusing. A simple household rule works well: one person records the payment, while the other checks the upcoming list. That gives the app a clear role instead of turning it into another source of disagreement.
Because the app includes in-app purchases ranging from $0.99 to $64.99 per item, I would also pay attention to any upgrade or optional purchase screen during setup. The basic app is free, so a new user can begin without treating payment as part of the initial learning process. I would first decide whether the everyday workflow is genuinely useful before considering anything extra.
Creating the first meaningful success
The first successful action should be more than installing the app or entering a bill. It should be completing one real cycle: add an upcoming payment, receive the reminder, make or schedule the payment through the appropriate provider, and then mark the item as paid in the app.
A realistic example would be a monthly internet bill. I would add it with a clear name, enter the expected due date and amount, and leave enough time to act before the deadline. When the reminder appears, I would pay through the provider I normally use, then return to the app and update the payment status. That final step is what turns a notification into a useful record.
After doing this once, I would look at the remaining upcoming bills and ask whether the next week is realistic. If several payments cluster together, the problem is not necessarily the app or the budget. It may show that money needs to be reserved earlier in the month. This is one of the less obvious benefits of tracking: the calendar of obligations can reveal pressure before the bank balance does.
For a household, the first success could be a short weekly check-in. One person opens the upcoming bills, the other confirms which payments have already been handled, and both agree on the next priority. That is more practical than trying to discuss the entire family budget every day.
Using reminders without creating notification fatigue
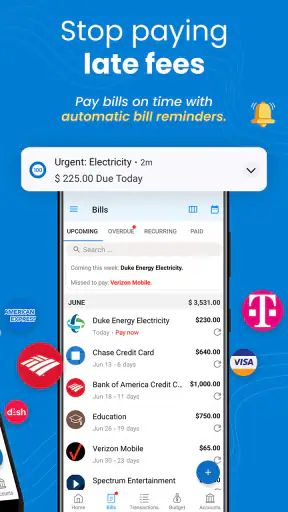
Reminders are helpful only when they arrive at a time you can act. If every bill produces noise long before it matters, you may begin dismissing all notifications. I recommend choosing a reminder routine that matches how you actually manage money. Someone paid weekly may want an earlier look at upcoming obligations, while someone paid monthly may prefer to review everything around payday.
The useful trade-off is between warning time and attention. A reminder that arrives too late offers little protection, but one that arrives too early can disappear into the background. I would start with one important bill and observe whether the timing changes my behavior. Then I would apply the same approach to other recurring payments instead of activating everything at once.
It is also worth separating “needs action” from “already handled.” Marking a bill as paid after completing it keeps the upcoming view focused. Leaving old items unresolved can make the app feel alarming even when your finances are fine. The quality of the information depends on this small maintenance habit.
Where new users may become confused
The phrase “payment reminder” can make people expect the app to pay bills automatically. I would not make that assumption. Think of it as a planning and tracking layer. You still need to use the relevant bank, card, or service provider to complete the payment, and you should verify important transactions independently.
Another possible confusion is the difference between a budget and a bill list. A bill tells you about a known obligation. A budget helps you decide how much money can be allocated across categories or goals. Entering rent and utilities is useful, but it does not by itself explain how much remains for groceries, transport, or unexpected costs. The budgeting side becomes meaningful when you use those obligations to shape the rest of the month.
Variable bills require judgment. If your electricity or phone amount changes, a fixed entry can give a false sense of accuracy. I would use a reasonable expected amount and leave room for variation, then update the figure when the actual charge is known. For households with highly unpredictable expenses, a spreadsheet may offer better control because it can model ranges and custom formulas more freely.
There is also a difference between recording a payment and proving that it happened. The app can help you remember and organize, but I would keep the provider confirmation or bank record for important transactions. That is especially sensible for rent, loans, insurance, and anything where a missed payment could have lasting consequences.
Turning the list into a monthly money routine
Once the initial bills are entered, I would use the app at three moments: when a new obligation appears, shortly before the main payment period, and after payments are completed. This rhythm keeps the information current without requiring constant attention.
When a new subscription or recurring charge begins, add it immediately rather than waiting for the next month. The delay between signing up and remembering to track it is exactly when small expenses tend to disappear from view. A monthly review can then show whether the service still deserves space in the budget.
Before payday or the start of a new month, I would inspect the upcoming obligations together. This is where the budget planner can be more useful than isolated reminders. The question is not simply “What is due?” but “What must be protected first, and what flexible spending can wait?”
After paying, update the record while the transaction is still fresh. If you postpone that step, several payments can blend together and the app loses its value as a current picture. This is a small workflow, but it is one of the concrete differences between a maintained finance tool and a forgotten one.
Family budgeting and shared responsibility
The family focus makes sense for households where money management is shared but not centralized. A couple can use the app to keep recurring obligations visible, while parents may use it to organize predictable household costs. I would avoid treating it as a replacement for a conversation about priorities, though. A shared list cannot decide whether a discretionary purchase is affordable or whether a financial goal matters more than another.
A good family workflow is to assign responsibility by category. One person can check housing and utilities, another can check subscriptions and school-related costs, and both can review the total before the payment period. This reduces duplicate work and makes it easier to notice an item that has not been updated.
The trade-off is that shared budgeting works only when everyone enters information consistently. If one person records every change and another relies on memory, the view will become incomplete. I would begin with a small group of recurring bills and agree on a weekly or monthly review rather than trying to manage every purchase from the first day.
How it compares with familiar alternatives
Compared with a paper notebook, this app is easier to use for dated reminders and recurring obligations. A notebook can be more flexible and private in a physical sense, but it depends heavily on manual checking. The app is better when the problem is forgetting a deadline rather than understanding complicated spending patterns.
Compared with a phone calendar, it offers a more finance-focused context. A calendar can remind you that a bill is due, but it does not naturally create a payment-tracking habit or bring household budgeting into the same workflow. If you only have two or three fixed bills, a calendar may be enough. If you want a connected view of bills and budgets, this app has the stronger fit.
Compared with a spreadsheet, the app is more approachable for someone who does not want to design formulas and monthly templates. A spreadsheet wins when you need custom categories, detailed historical analysis, or unusual calculations. I would choose the app for routine household organization and a spreadsheet for deeper financial modeling.
Compared with a bank’s own tools, the app may be more useful when you want to think across several accounts or providers. A bank view can be excellent for transactions within that institution, but household obligations often span multiple services. The trade-off is that a dedicated organizer depends on you keeping entries current instead of receiving every detail automatically from one financial account.
Who should use it, and who should skip it
I think it is a good choice for first-time budgeters, busy households, and anyone who repeatedly misses recurring payment dates. It has enough structure to create a dependable routine without forcing a beginner to learn accounting terminology. The free starting point also makes it reasonable to test with a few bills before committing to a larger system.
I would be more cautious if you want automatic bank synchronization, advanced investment tracking, business accounting, or highly detailed spending reports. People who already maintain a reliable spreadsheet may not gain much unless reminders and a simpler mobile workflow are the main attraction.
It may also be the wrong fit for someone who dislikes manual updates. The app can organize information, but it cannot make an incomplete bill list accurate. If you will not record new obligations or mark completed payments, a simpler calendar alert may actually be more effective because it demands less maintenance.
My recommendation after building a routine
Bill Payment Reminder, Budgets works best when you keep its job clear: it is a personal and family organizer for bills, budgets, and payment follow-through. I like that it encourages a practical sequence rather than leaving money management as a vague intention. Add the obligation, prepare for it, complete the payment elsewhere, and update the record.
Its limitations are tied to that same simplicity. It is not a bank, not a guarantee that a payment succeeded, and not a replacement for detailed accounting. Variable expenses and complex financial situations may require another tool alongside it. The app also asks for regular input, which some users will find less convenient than automatic financial aggregation.
For a first-time user, I would install it, add only the most important upcoming bills, and aim to complete one reminder-to-paid cycle before entering everything else. That gives you a meaningful test instead of a crowded setup screen. If the routine helps you reserve money earlier and stop forgetting deadlines, it has earned a permanent place in your monthly planning.
Overall, I see this free finance app as a sensible middle ground between a basic calendar and a demanding spreadsheet. TimelyBills has focused it on a problem many people genuinely have: keeping recurring obligations visible and manageable. With a little consistency, it can make the next payment easier to anticipate and the household budget easier to discuss.
Pros
- Simple interface makes recurring bill tracking quick and easy.
- Custom reminders help reduce the risk of missed payment deadlines.
- Budget tools provide a clearer view of monthly spending limits.
- Supports planning for irregular expenses and upcoming financial obligations.
- Useful overview for managing multiple bills in one place.
Cons
- Some advanced features may require a premium subscription.
- Manual entry can be time-consuming when adding many bills.
- Reminder accuracy depends on correct dates and notification permissions.
- May not support every local biller, currency, or payment method.
- No app can guarantee payments unless you complete them yourself.
FAQs for Bill Payment Reminder, Budgets
What is Bill Payment Reminder, Budgets, and what can I use it for?
Bill Payment Reminder, Budgets is designed to help you organize recurring bills, monitor spending, and plan your monthly finances from one place. After reviewing the app, its main purpose is to give you a clearer view of upcoming payments and available funds. You can use it to record bills, set reminders, track budget categories, and reduce the chance of missing important due dates.
How do I add bills and set payment reminders in the app?
Adding a bill is generally straightforward: enter the bill name, amount, due date, and payment frequency, then save it to your list. You can usually create recurring entries for expenses such as rent, utilities, subscriptions, loans, or insurance. Reminder notifications help alert you before a payment is due, although you should check your device notification permissions to ensure alerts are not blocked.
Can Bill Payment Reminder, Budgets track my spending and help me create a budget?
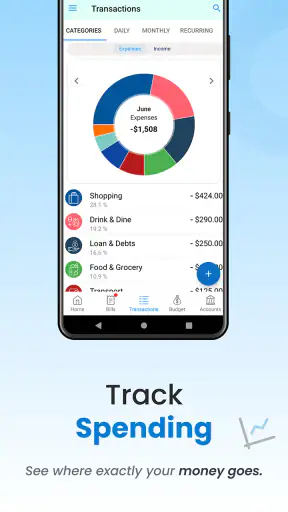
Yes, the app is intended to support basic personal budgeting by letting you organize expenses into categories and compare planned amounts with actual spending. This can make it easier to identify recurring costs and areas where you may be overspending. It should be viewed as a planning and tracking tool rather than a replacement for professional financial advice or a complete banking service.
Is my financial information safe when using Bill Payment Reminder, Budgets?
Before entering sensitive information, review the app’s privacy policy, permissions, and data-handling details on the official store listing. A bill reminder app normally does not need your online banking password or full payment credentials, so avoid adding information that is not required. Also protect the device with a passcode or biometric lock, and keep the application updated for the latest security improvements.
Does the app make payments automatically, or does it only remind me?
Bill Payment Reminder, Budgets should not be assumed to pay bills automatically unless the app clearly provides and explains a supported payment integration. Its primary function is to record obligations, organize budgets, and notify you about approaching due dates. You remain responsible for completing each payment through your bank, service provider, or preferred payment platform and for confirming that the transaction was successful.

Bill Payment Reminder, Budgets
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@timelybills.app, visit https://timelybills.app/, or review their https://timelybills.app/privacy-policy.










